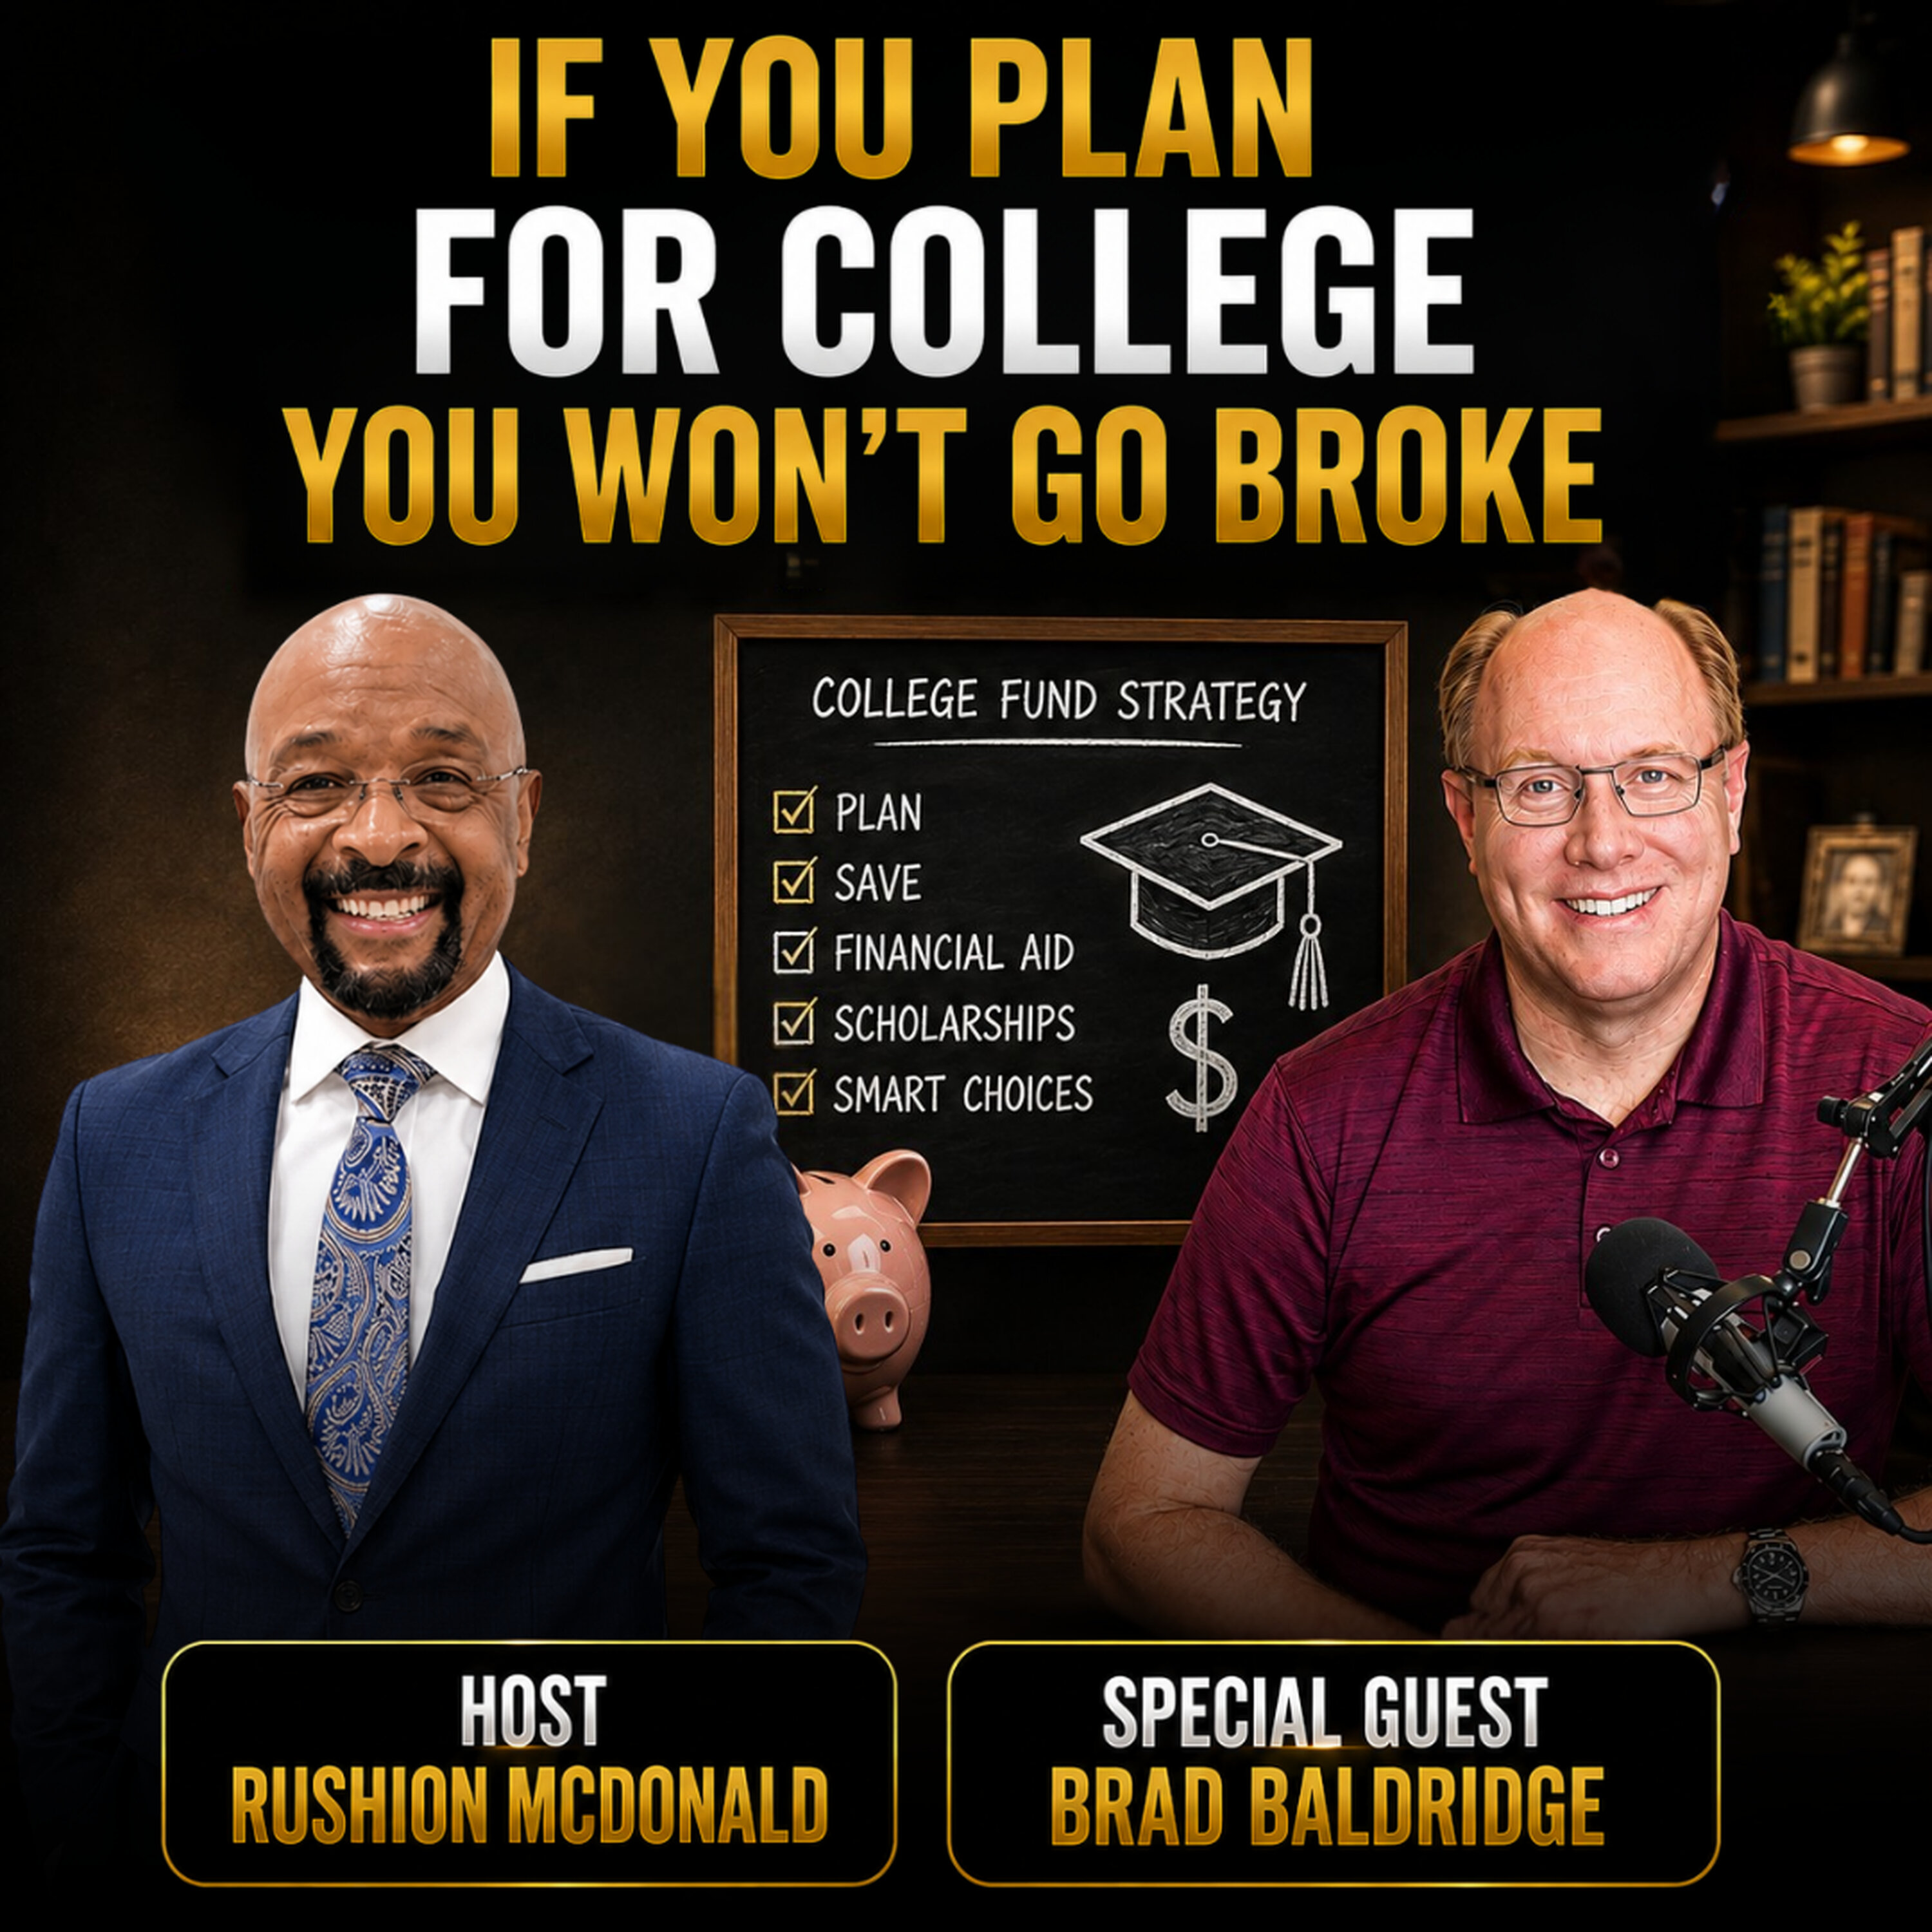
Don't pay for college, helping students get college scholarship and financial aid by Brad Baldridge.
Listen and subscribe to Money Making Conversations on iHeartRadio, Apple Podcasts, Spotify, www.moneymakingconversations.com/subscribe/ or wherever you listen to podcasts. New Money Making Conversations episodes drop daily. I want to alert you, so you don’t miss out on expert analysis and insider perspectives from my guests who provide tips that can help you uplift the community, improve your financial planning, motivation, or advice on how to be a successful entrepreneur. Keep winning!
Two-time Emmy and Three-time NAACP Image Award-winning television Executive Producer Rushion McDonald interviewed Brad Baldridge.
a certified financial planner and college funding expert who has spent more than 20 years helping families plan, save, and pay for college. The conversation focuses on understanding financial aid, scholarships, college costs, student loans, and how families can make smarter financial decisions without sacrificing their retirement goals.
The interview serves as a practical guide for parents who want to help their children attend college while avoiding unnecessary debt and financial stress.
About Brad Baldridge
Brad Baldridge is:
- Certified Financial Planner (CFP)
- College Planning Expert
- Financial Aid Strategist
- Host of the Taming the High Cost of College Podcast
- College Funding Consultant
For more than two decades, he has helped families:
- Understand financial aid
- Identify college savings strategies
- Find scholarships
- Compare college costs
- Reduce student debt
- Create college payment plans
His primary goal is helping families make informed financial decisions before committing to expensive college options.
Why He Specialized in College Planning
Brad began his career as a traditional financial planner.
Over time, he noticed that many families lacked guidance when it came to paying for higher education.
Parents frequently asked questions such as:
- How does financial aid work?
- What scholarships are available?
- Should we take out loans?
- How much should we save?
- Which colleges offer the best financial packages?
The more he worked with families, the more he realized there was a significant need for specialized college planning advice.
Understanding the Different Types of College Funding
One of the first topics discussed was the confusion surrounding college financial assistance.
Brad explained that several different funding sources exist:
Need-Based Financial Aid
Financial aid awarded based on a family's:
- Income
- Assets
- Financial circumstances
Most families encounter this through:
FAFSA (Free Application for Federal Student Aid)
Merit-Based Aid
Merit aid is awarded based on:
- Academic achievement
- Leadership
- Special talents
- School-specific criteria
Unlike need-based aid, family income may play little or no role.
Athletic Scholarships
Scholarships based on athletic performance and recruitment.
However, Brad emphasized that only a small percentage of students qualify for significant athletic scholarships.
Student Loans
Loans can fill funding gaps when grants and scholarships are insufficient.
However, loans should be viewed as:
A tool, not a solution.
Are Student Loans Bad?
One of the most important questions in the interview was:
Are student loans always a bad idea?
Brad's answer was:
No.
He compared loans to tools in a toolbox.
A loan can be useful when:
- Used appropriately
- Managed responsibly
- Supported by a repayment plan
The real danger occurs when families borrow without fully understanding the long-term consequences.
Lesson
Student loans are neither inherently good nor bad. The key is using them strategically.
The Biggest Cost Mistake Parents Make
Many families focus solely on:
The published college price.
Brad explained that the published tuition often has little connection to what families actually pay.
Different students may receive:
- Grants
- Scholarships
- Institutional aid
- State programs
As a result, the actual cost can vary dramatically.
The Stanford Example
Brad used Stanford University as an example.
Although its listed annual cost may exceed $80,000, many lower-income students pay little or nothing because of financial aid programs.
At the same time:
- Higher-income families may receive little assistance.
- They often pay the full listed amount.
Lesson
Parents should always evaluate:
Net Cost
not simply:
Sticker Price
Similar Schools Can Have Very Different Prices
A major takeaway was that colleges with comparable academic reputations can have significantly different costs.
For example:
- One school may cost $25,000 per year.
- Another may cost $55,000 per year.
- Both may offer similar educational outcomes.
Families often overlook lower-cost options because they assume more expensive schools automatically provide better value.
Every Family's Situation Is Different
Brad emphasized that there is no universal college payment strategy.
Factors that influence decisions include:
- Family income
- Savings
- Academic performance
- Athletic ability
- Number of children
- Retirement planning
- State residency
What works for one family may not work for another.
The Importance of Early Planning
One of Brad's strongest recommendations:
Start earlier than you think.
Many families wait until:
- Senior year
- College application season
before learning about financial aid.
By then, many opportunities may already be limited.
Brad recommends beginning as early as:
- Freshman year of high school
- Sophomore year of high school
for meaningful planning.
What Is Late-Stage College Planning?
Rushion asked Brad to explain:
Late-Stage College Planning
According to Brad, this refers to the years immediately before college enrollment.
The focus shifts from saving money to making decisions about:
- College selection
- Financial aid
- Scholarships
- Loans
- Payment strategies
At this stage families need detailed planning rather than general savings advice.
s
You May Also Like

Les Nuits de France Culture
France Culture
Ça peut vous arriver
RTL
Thomas Paine Podcast
mike moore
Thrilling Threads - Conspiracy Theories, Strange Phenomena, Unsolved Mysteries, etc!
Byte & Pieces
Affaires sensibles
JEROME GUEDON
The Vince Everett Ellison Show
Media Squatch
The Daily Horoscope
The Daily Horoscope
Rogue Energy
iHeartPodcasts

Tilos Rádió heti podcast
Tilos Rádió
True Cheating Wives and Girlfriends Stories 2025 - True Cheating Stories Podcast
True Cheat Stories Official 2026
Les Nuits de France Culture
France Culture
Ça peut vous arriver
RTL
Thomas Paine Podcast
mike moore
Thrilling Threads - Conspiracy Theories, Strange Phenomena, Unsolved Mysteries, etc!
Byte & Pieces
Affaires sensibles
JEROME GUEDON
The Vince Everett Ellison Show
Media Squatch
The Daily Horoscope
The Daily Horoscope
Rogue Energy
iHeartPodcasts
Tilos Rádió heti podcast
Tilos Rádió
True Cheating Wives and Girlfriends Stories 2025 - True Cheating Stories Podcast
True Cheat Stories Official 2026
Community discussion